1. Property Taxes
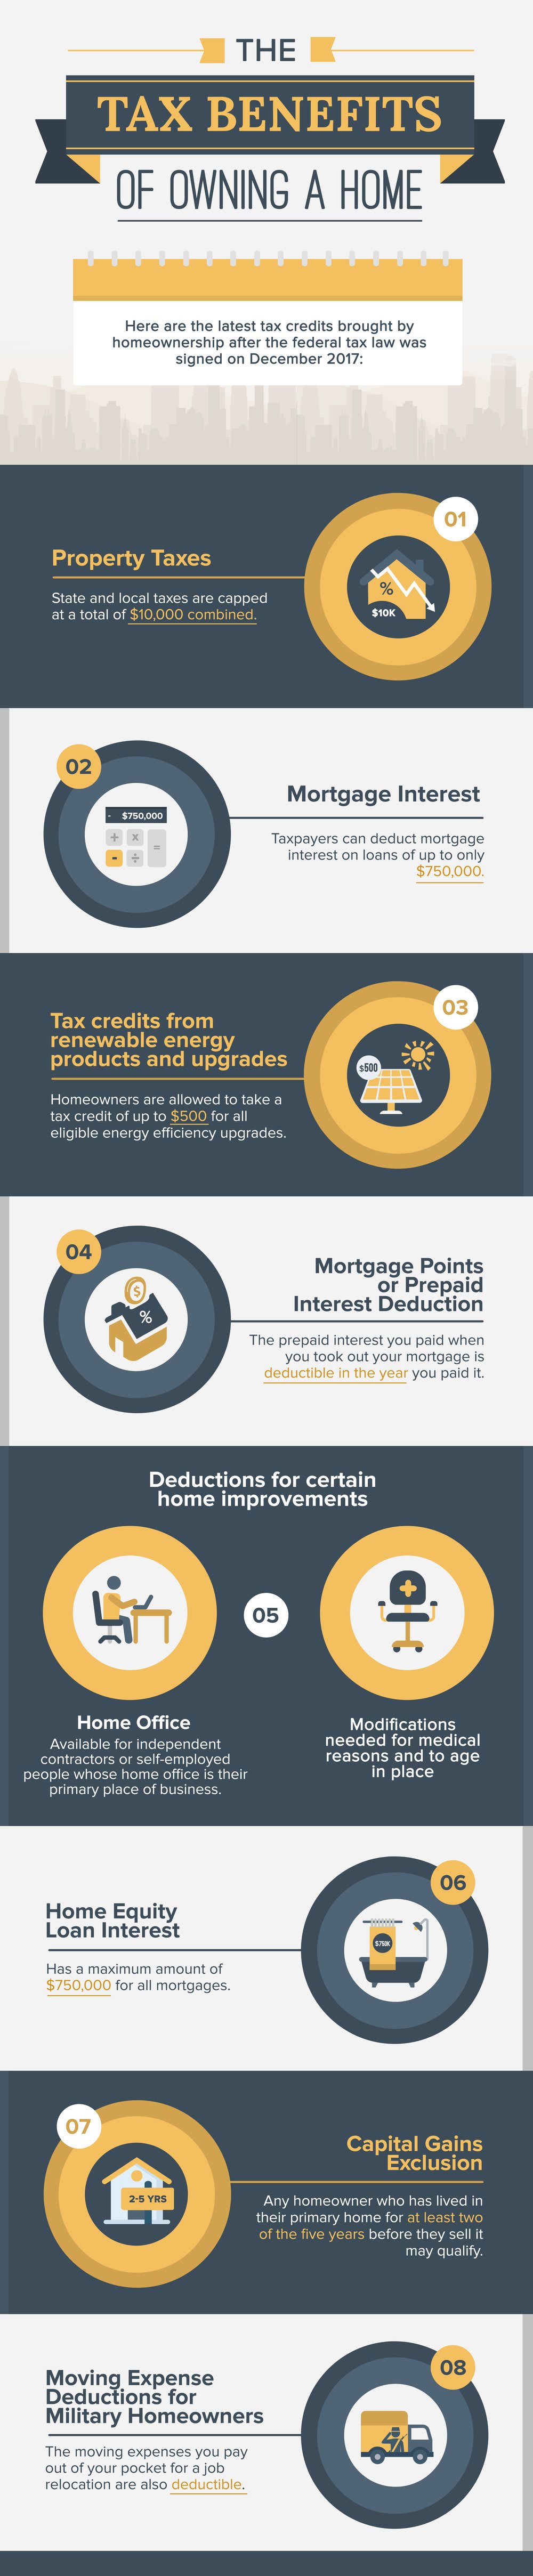
Back in 2017, the deductions for property taxes were unlimited. All of your property taxes are deductible, so if you live in an area where the property taxes are high, you could wind up deducting thousands of dollars.
Likewise, this tax deduction can still be helpful for your finances, although it can be tricky in the year you bought the home. As the buyer and new homeowner, you will only get to deduct the property taxes you owed for the portion of the year you owned the home. The seller gets the rest of the deduction, regardless if you offered to pay the full year of property taxes during negotiations.
2. Mortgage Interest
Many homeowners can deduct the interest portion of their monthly mortgage payments each year. It remains as a deductible under the new tax plan but with a new cap. Taxpayers are now allowed to deduct mortgage interest on loans of up to only $750,000, compared to the previous $1 million. The maximum mortgage debt on which you can deduct the interest also applies to secondary or vacation homes.
3. Tax Credits from Renewable Energy Products and Upgrades
Homeowners who have installed alternative energy upgrades in their homes may qualify for tax credits as long as the products installed are also eligible. Most of these deductions are still available through December 31, 2021, such as the credits for solar electric and solar water heating equipment.
4. Mortgage Points or Prepaid Interest Deduction
If you itemize your deductions on Schedule A of IRS Form 1040, the prepaid interest you paid when you took out your mortgage is deductible in the year you paid it. Paying the prepaid interest or points makes more sense if you plan to stay longer in your home, as they can bring down the interest rate on your loan or help with origination fees. This is a one-time deduction that many homeowners can take advantage of — just remember that it is often deductible in the first year.
5. Deductions for Certain Home Improvements
- Home Office
If you are using a part of your home regularly and exclusively for business, you may qualify for some tax breaks. With the new tax law, the home office deduction remains available for independent contractors or self-employed people whose home office is their primary place of business. However, if you're an employee who has an office to go to but occasionally works from home, this deduction has been repealed.
- Modifications needed for medical reasons and to age in place
For older homeowners who have medical concerns and plan to age in place, their home remodeling projects could involve modifications to support these needs. The projects may vary but could include installing wheelchair ramps, non-skid flooring, adding stair lifts, widening doorways, and even putting grab bars, shower seats, and anti-slip coating in bathrooms. The good news is that the cost of these modifications can be deductible.
6. Home Equity Loan Interest
Home equity loans or HELOCs allow you to get a tax break on the interest you pay. However, the deduction is applicable only if you’re planning to use it for major home improvements, like remodeling a bathroom or renovating a fixer-upper. It also has a maximum amount for all mortgages, which is $750,000.The tax benefits of this credit will be most significant to any homeowner for the first years of the loan since most of the payments are going toward interest.
7. Capital Gains Exclusion
Any homeowner who has lived in their primary residence for at least two of the five years before they sell it may qualify for this tax break. The IRS may exempt up to $250,000 if you’re single, or $500,000 if you’re married filing jointly, of that gain from your income. This is to lessen the tax hit on taxable capital gains from the sale of your property. This advantage stays the same under the new tax law, and there’s no restriction on how many times you can use it.
8. Moving Expense Deductions for Military Homeowners
The moving expenses you pay out of pocket for a job relocation, especially if it’s over 50 miles farther from your house than your current job, are also deductible.